Refrigerated truck operators face unique insurance challenges that standard commercial policies simply don’t address. Temperature failures, spoilage losses, and mechanical breakdowns can wipe out your profit margins in hours.
At Insurance Brokers of Arizona®, we’ve seen firsthand how the right refrigerated truck insurance protects your cargo and your bottom line. This guide walks you through what coverage you actually need and how to find it.
What Your Refrigerated Truck Policy Actually Covers
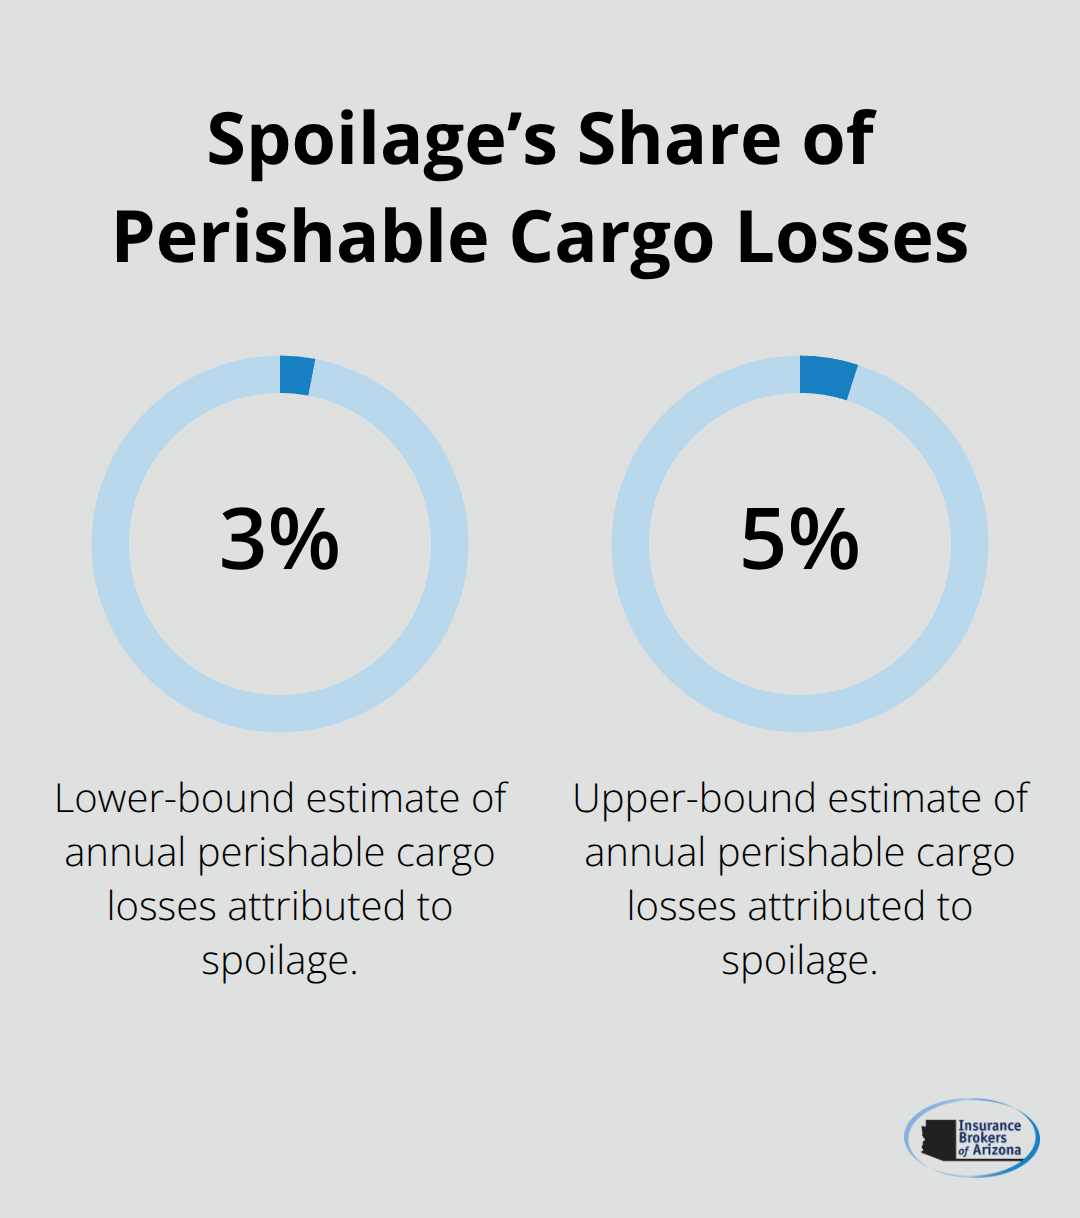
Refrigerated truck insurance splits into three distinct protection areas, and understanding each one matters because gaps in coverage can cost thousands when problems arise. Cargo protection covers the perishable goods you transport, compensating you when products spoil due to temperature fluctuations, equipment failure, or accidents. This isn’t a standard add-on to regular commercial policies. The American Trucking Associations reports that spoilage accounts for roughly 3 to 5 percent of perishable cargo losses annually, which translates to significant financial exposure for operators. Your policy should specify coverage limits based on your typical shipment values, and these limits need to increase during peak seasons when you move higher-value loads.
Vehicle Damage and Liability Coverage
Vehicle damage and liability coverage protects your truck itself along with your legal responsibility if you damage someone else’s property or injure someone. This includes collision, comprehensive, and uninsured motorist protection for your refrigeration unit, which is expensive to repair and critical to your operation. Liability coverage in refrigerated transport should be higher than standard commercial trucking because a spoiled shipment affecting a restaurant or grocery chain can trigger substantial claims. Your policy documents should clearly outline these limits so you know exactly what protection you have when accidents happen.
Temperature Failure Protection Separates Good Policies from Inadequate Ones
Breakdown coverage specifically addresses what happens when your refrigeration system fails mid-transit. This is where most operators discover their standard policy leaves them exposed. Temperature control failures can destroy an entire load within hours, and without proper coverage, you absorb the total loss. Some policies include coverage for the cost of transferring cargo to another refrigerated vehicle, which can run $500 to $2,000 depending on distance and urgency.
Your policy should clearly state whether it covers mechanical breakdowns, electrical failures, and compressor malfunctions. Many operators overlook that coverage limits for breakdown repairs often differ from coverage limits for cargo loss, so you need both spelled out in your policy documents. Coverage for these specific failure points matters far more than generic commercial coverage that leaves critical gaps unaddressed.
Understanding what your policy actually covers sets the foundation for choosing the right protection. The next step involves assessing your specific cargo values and routes to determine how much coverage you truly need.
Key Risks Refrigerated Truck Operators Face
Spoilage Destroys Entire Loads in Hours
Spoilage happens fast, and the numbers tell the story. The U.S. Department of Agriculture estimates that food waste in the cold chain costs the industry roughly 15 to 20 percent of total perishable shipments annually. A single temperature excursion lasting just four hours can render an entire truckload of seafood, dairy, or produce worthless. Operators we work with have lost $50,000 to $150,000 on single shipments due to refrigeration failures or accidents that broke the cold chain. The reality is that spoilage doesn’t discriminate between new operators and experienced ones. Your cargo sits in a metal box traveling at highway speeds, dependent entirely on a mechanical system that can fail without warning. When it does, you lose the product cost, the margin, face customer penalties, and potentially deal with breach of contract claims if your shipment was promised to a specific buyer with strict temperature requirements.
Mechanical Failures Strike Without Warning
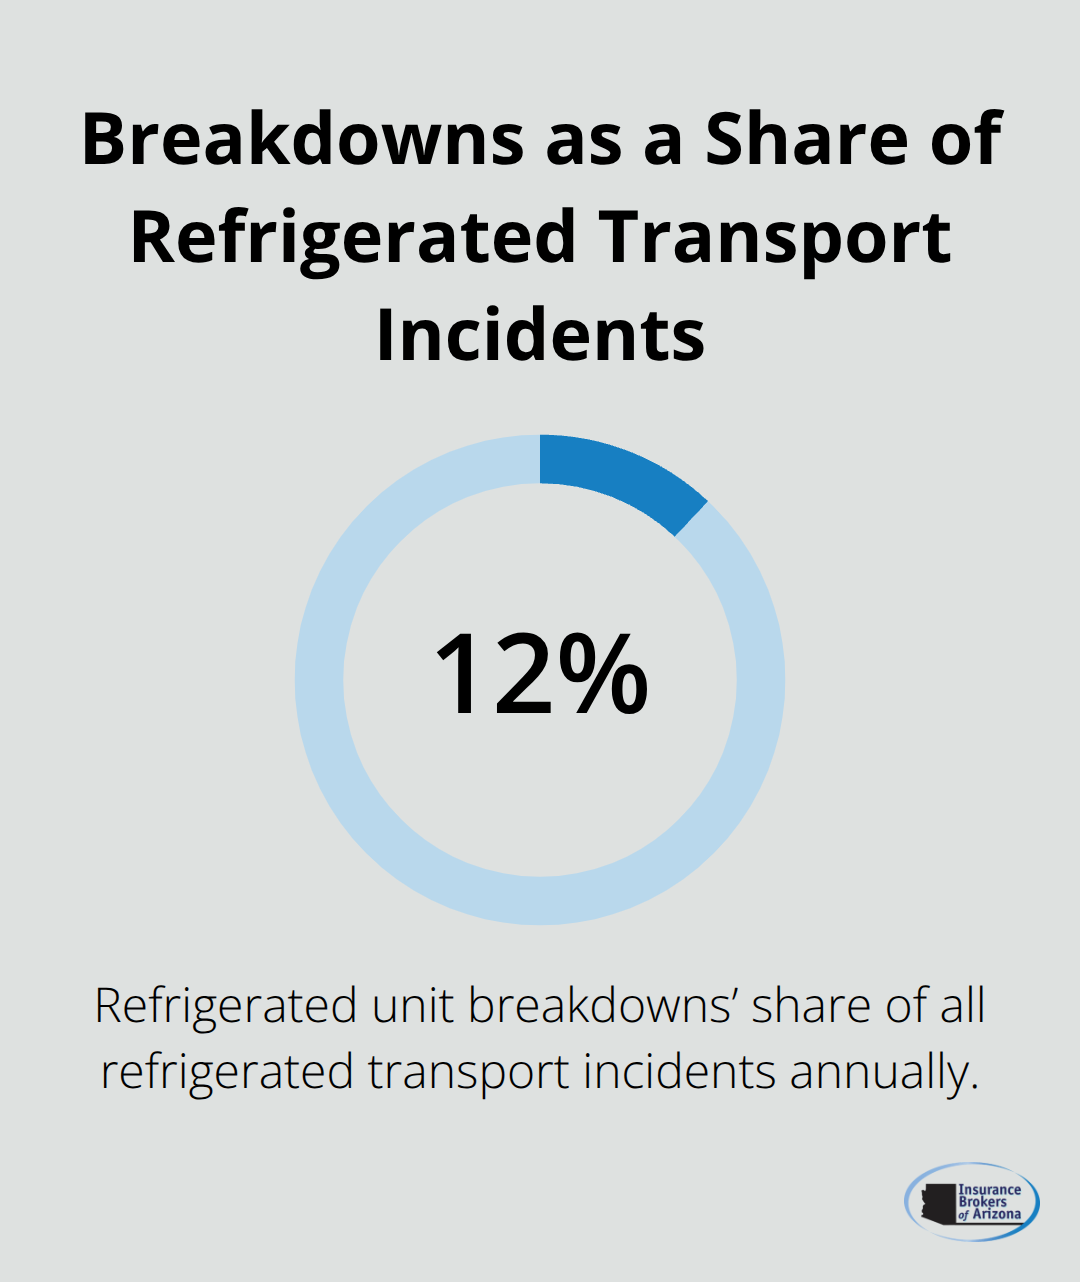
Mechanical failures during transit represent a major threat, and they occur more often than most operators expect. The American Trucking Associations reports that refrigerated unit breakdowns account for approximately 12 percent of all refrigerated transport incidents annually. Compressor failures, electrical system malfunctions, and refrigerant leaks disable your equipment without announcement.
A failed compressor repair costs between $3,000 and $8,000, and that’s just the equipment. If you haul temperature-sensitive cargo, you face the immediate decision of transferring your load to another refrigerated vehicle or abandoning it entirely. Roadside repairs for refrigeration units often run premium prices because specialized technicians remain scarce in rural areas. A breakdown 200 miles from the nearest qualified technician can turn into a $15,000 problem before you factor in the lost cargo.
Accidents Create Cascading Liability Exposure
Accidents and liability claims round out the risk picture, particularly because refrigerated transport often means higher-value cargo traveling on tight schedules. A collision that spills perishable goods across a highway creates cleanup costs, potential environmental claims, and customer liability for spoiled product. Your liability exposure increases significantly when your shipment was destined for a major food retailer or restaurant chain with strict delivery windows and high financial stakes. These scenarios demand coverage that addresses both the immediate accident costs and the secondary losses that follow.
Understanding these specific threats shapes how you should structure your insurance protection. The right policy addresses each risk directly rather than leaving gaps that cost thousands when problems arise.
How to Choose the Right Refrigerated Truck Insurance
Match Your Coverage Limits to Your Actual Cargo
Selecting refrigerated truck insurance requires matching your coverage limits to what you actually haul and where you haul it. Many operators grab a policy based on price alone, then discover critical gaps when claims hit. Start by calculating your typical shipment values across a full year, separating peak season from off-season loads. If you haul seafood worth $80,000 per truckload during summer months but produce worth $35,000 during winter, your cargo coverage limits need to reflect these variations. Some carriers allow seasonal adjustments to your policy, which costs less than maintaining year-round coverage for peak-season values.
Document your highest-value shipments from the past two years, your average load values, and your most frequent routes. This data becomes your foundation for conversations with insurance providers because vague estimates lead to inadequate coverage. Routes matter equally because interstate hauling across multiple states versus regional Arizona routes carry different liability exposures and mechanical risks. A long-haul route from Phoenix to California exposes you to more breakdown scenarios than a 200-mile regional route, and your coverage should account for that difference.
Compare Multiple Carriers to Identify Coverage Gaps
Comparing carriers directly reveals massive variations in what they cover and what they charge. Reports indicate that premiums for refrigerated transport policies vary by as much as 40 percent across carriers for identical coverage, so shopping multiple options saves thousands annually. Request quotes from at least three carriers, but structure your requests identically so you can actually compare apples to apples. Specify your exact cargo types, your average load values, your annual mileage, your driver experience, and your desired deductibles.
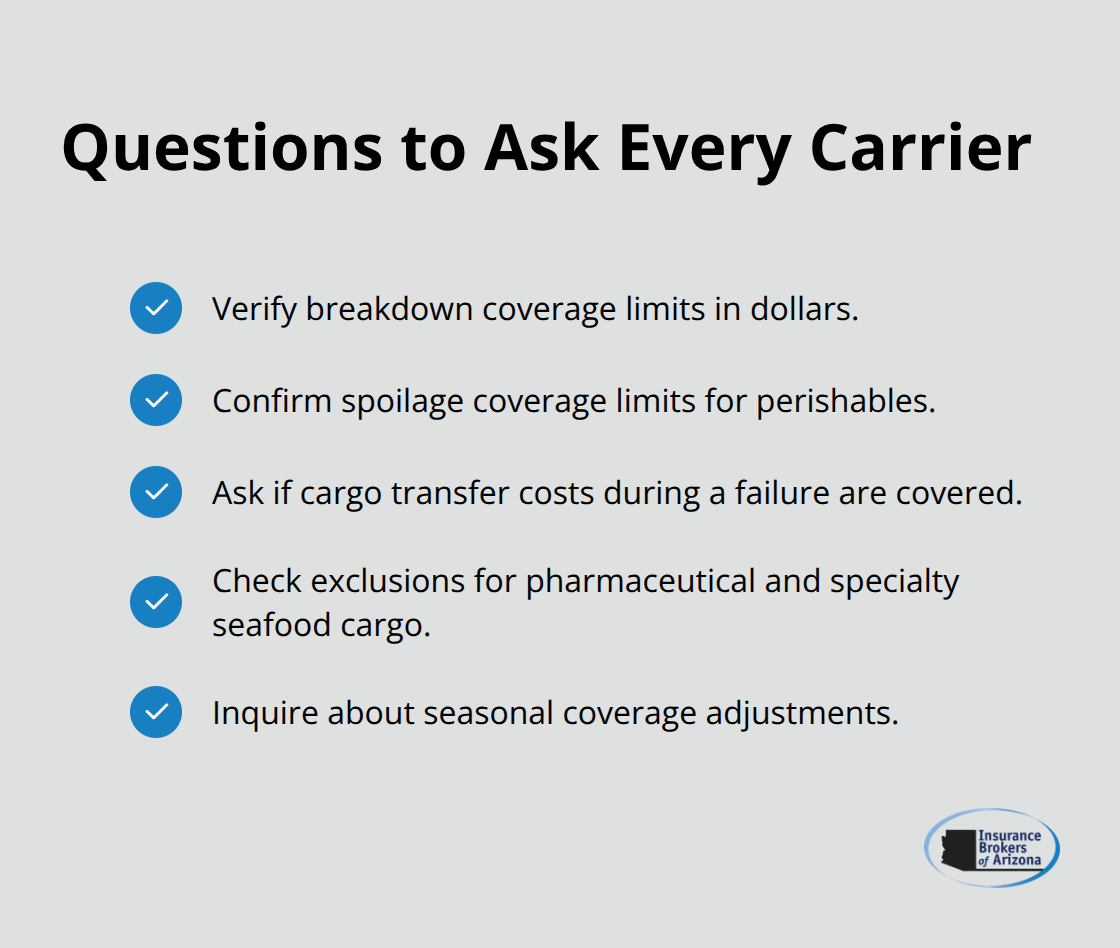
Ask each carrier specifically about breakdown coverage limits, spoilage coverage limits, and whether they cover cargo transfer costs if your refrigeration fails mid-transit. Some carriers exclude certain perishable categories like pharmaceutical products or specialty seafood, so you need those details upfront. Operators who compare five or more quotes typically secure 25 to 35 percent better rates than those accepting the first offer, and more importantly, they identify coverage gaps that single-quote shopping misses entirely. Don’t settle for a broker who quotes one or two carriers and calls it done.
Final Thoughts
Refrigerated truck insurance protects your operation when equipment fails, cargo spoils, or accidents happen. The risks are real, the losses are substantial, and standard commercial policies leave you exposed to exactly the scenarios that destroy operators. Your coverage must address cargo protection that compensates you when perishables spoil, vehicle and liability coverage that protects your truck and legal exposure, and breakdown protection that covers temperature failures mid-transit.
The operators who protect themselves best match their coverage limits to actual cargo values, compare multiple carriers to identify what each one covers and what they charge, and work with someone who understands refrigerated transport specifically. Generic insurance brokers miss critical details that specialists catch immediately-they know which carriers exclude pharmaceutical products, which ones cover cargo transfer costs, and which ones adjust coverage seasonally so you avoid overpaying during slower months. A single spoilage event costing $100,000 or a mechanical failure requiring a $15,000 roadside repair becomes catastrophic if your policy has gaps.
Contact Insurance Brokers of Arizona® to discuss your refrigerated truck insurance needs. We’ll review your cargo values, your routes, and your current coverage to identify gaps and secure protection that matches your operation.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.