Your belongings matter, and so does protecting them. Most Arizona renters assume their landlord’s insurance covers their personal property-it doesn’t.
An Arizona renters policy is one of the most affordable ways to guard your possessions, cover liability if someone gets hurt in your unit, and stay afloat if disaster strikes. We at Insurance Brokers of Arizona® help renters understand exactly what they need and why it matters.
What Your Arizona Renters Policy Actually Protects
Three Core Protections Working Together
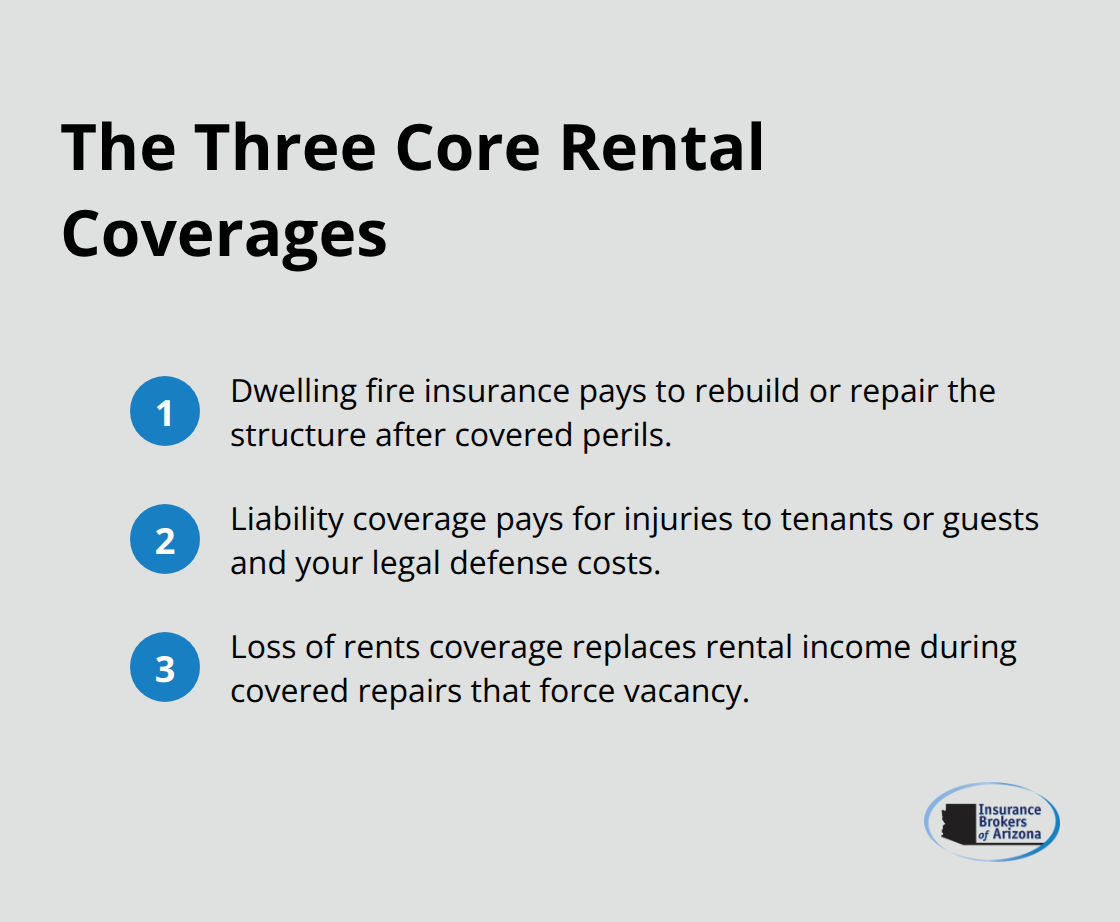
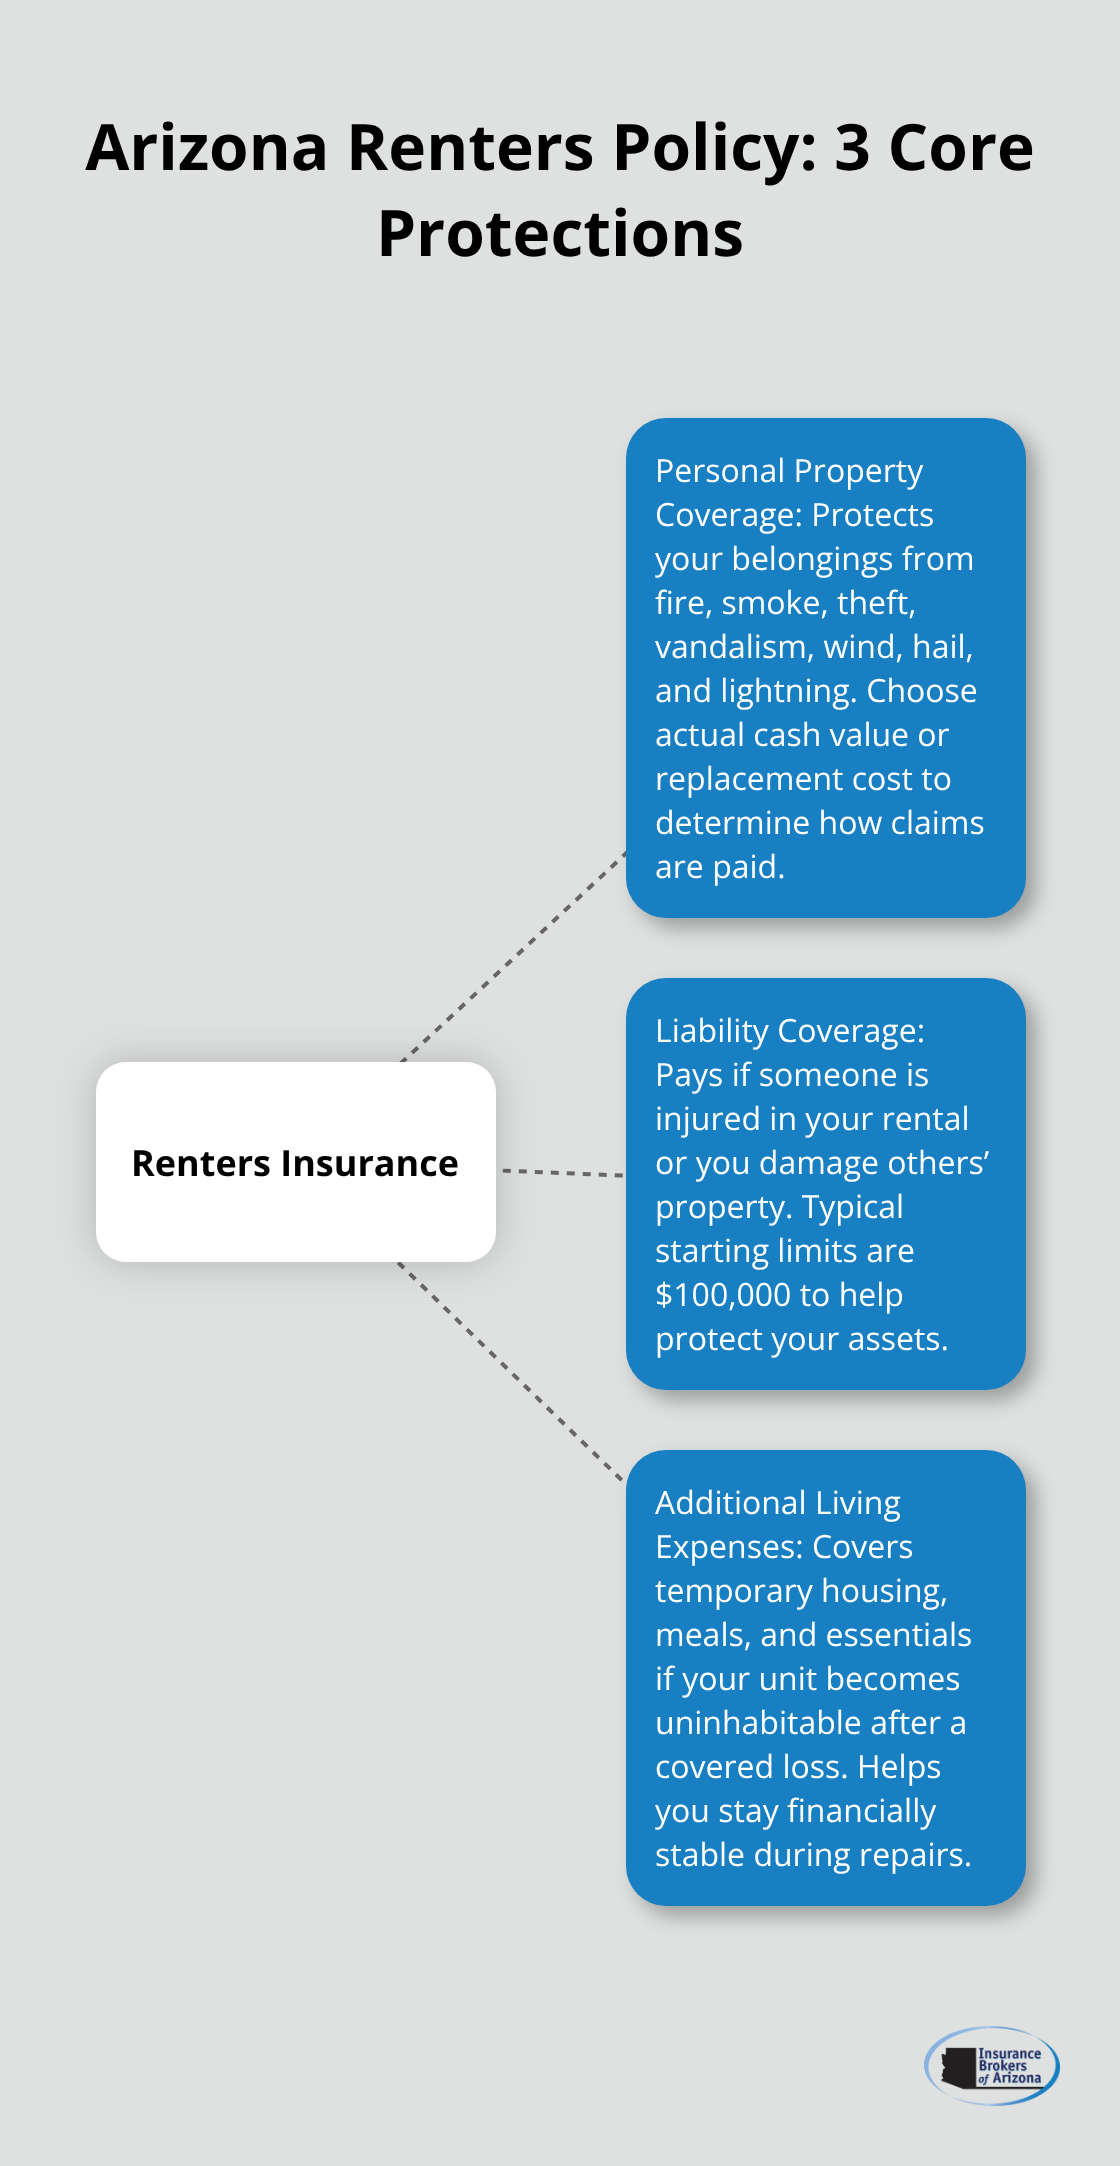
An Arizona renters policy covers three distinct areas that work together to shield you financially. Personal property coverage protects your belongings from fire, smoke, theft, vandalism, wind, hail, and lightning. If a burglar steals your laptop from your Tucson apartment or a burst pipe floods your furniture, this coverage reimburses you. You choose between actual cash value, which pays out what items are worth after depreciation, or replacement cost coverage, which pays to replace items at today’s prices.
Personal Property Coverage and What You Need
Most Arizona renters need between $20,000 and $40,000 in personal property coverage, though this varies based on what you own. The National Association of Insurance Commissioners reports that renters policies average around $185 annually nationwide, with Arizona renters paying as low as $15 to $30 per month depending on coverage limits and location. Cataloging your belongings by taking photos and listing replacement costs helps you determine how much coverage you actually need. This inventory becomes essential when filing a claim and prevents you from under-insuring your possessions.
Liability Coverage Protects You From Others’ Claims
Liability coverage is the second major component and covers you if someone gets injured in your rental or you accidentally damage their property. If a guest trips on your stairs and breaks their arm, or you cause water damage to a neighbor’s unit, liability coverage pays their medical bills and property repairs up to your policy limit. Most policies start with $100,000 in liability protection, which serves as a solid minimum. The third component, additional living expenses coverage, pays for temporary housing, meals, and other costs if your unit becomes uninhabitable after a covered disaster.
High-Value Items and Coverage Gaps
High-value items like jewelry, electronics, and artwork often exceed standard coverage limits. If you own a $3,000 engagement ring or expensive camera equipment, you’ll want to add a rider or endorsement to your policy for full replacement cost. Water damage from burst pipes is covered, but flood damage from heavy rain or monsoon season is not, which matters significantly in Arizona given our summer monsoon risks. Earthquake damage is also excluded from standard policies, though you can purchase separate earthquake coverage.
Discounts and Shopping Strategy
Discounts exist for bundling renters with auto insurance, paying your premium upfront, or installing security features like deadbolts or alarm systems. Getting multiple quotes from different carriers is non-negotiable because premiums vary significantly based on your ZIP code, building type, and the specific coverage options you select. Once you understand what coverage protects you, the next step involves assessing your personal property value and comparing quotes to find the right policy for your situation.
Why Arizona Renters Skip This Coverage
Landlord Insurance Covers the Building, Not Your Stuff
Most Arizona renters believe their landlord’s insurance protects their belongings-this misconception stands as the single biggest reason they skip renters coverage entirely. Landlord insurance covers the building structure and the landlord’s liability, not your personal property. A burst pipe floods your apartment, and the landlord’s policy pays to fix the building, but your destroyed furniture, electronics, and clothing remain your responsibility. A guest trips on your stairs and gets injured; the landlord’s liability coverage may not apply to tenant-caused incidents. Many landlords carry minimal liability limits anyway, leaving gaps that expose you to direct lawsuits. This confusion costs renters thousands annually when disaster strikes.
You Own More Than You Think
The second barrier is underestimating what you actually own. Most people guess they have $8,000 to $12,000 in belongings, then realize during a claim that they own $30,000 to $40,000 worth of possessions. Your electronics alone-laptop, phone, tablet, television, gaming console-total $3,000 to $5,000 quickly. Furniture, clothing, kitchen appliances, and tools add up fast. The National Association of Insurance Commissioners reports that renters policies average $185 annually nationwide, yet many Arizona renters pay as little as $15 to $30 per month for adequate coverage. This low cost exists because renters insurance is genuinely affordable, not because it’s inadequate.
The Real Cost of Skipping Coverage
The third barrier is cost perception, which directly contradicts reality. Many renters believe they cannot afford protection when Arizona policies cost less than a streaming subscription. Bundling renters with auto insurance yields even steeper discounts-some carriers offer up to 20 percent off renters premiums when combined with auto coverage. Paying your premium annually rather than monthly typically reduces your total cost by 5 to 10 percent. The real expense happens when renters skip coverage and face complete loss. A theft, fire, or water damage event forces you to replace everything from your personal funds, which costs far more than years of premiums combined.
Moving Forward With the Right Protection
Understanding why renters skip coverage reveals the path forward. The misconceptions fade once you see what landlord insurance actually covers, the true value of your belongings becomes clear through a simple inventory, and the affordability of protection becomes undeniable when you compare actual quotes. The next step involves assessing your personal property value and comparing quotes to find the right policy for your situation.
How to Choose the Right Coverage for What You Actually Own
Create an Accurate Inventory of Your Belongings
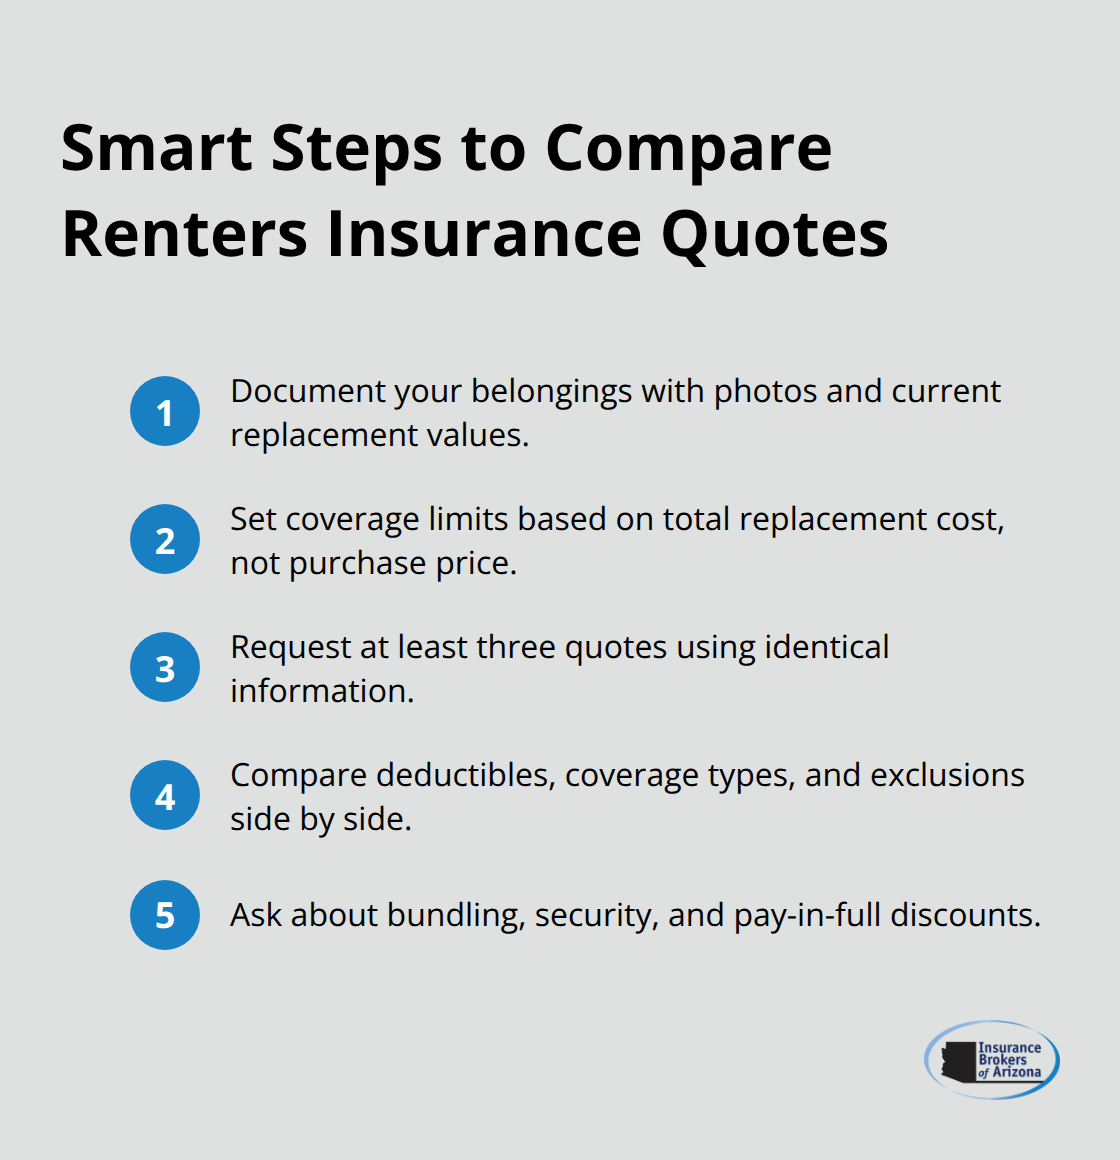
Start with a real inventory of your belongings, not a rough guess. Walk through your apartment and photograph items in each room, then note replacement costs for major possessions. Your electronics typically represent 20 to 30 percent of your total value, so list your laptop, phone, tablet, television, and gaming systems first. Furniture costs more than most renters expect; a decent sofa runs $1,200 to $2,000, a bedroom set adds another $1,500 to $3,000, and kitchen appliances easily total $1,000 to $2,000. Clothing, shoes, and accessories accumulate fast when you assign realistic replacement prices rather than what you paid years ago.
Most Arizona renters discover they need $30,000 to $40,000 in coverage once they complete this exercise, which is significantly higher than their initial estimates. Once you know your actual property value, you can select coverage limits that prevent catastrophic financial loss.
Compare Quotes From Multiple Carriers
Comparing quotes reveals why selecting the right carrier matters more than picking the cheapest option. Premiums vary dramatically based on your ZIP code, building type, and the specific coverage you select, so a quote from one carrier tells you almost nothing about what another will charge. Contact at least three different insurers and provide identical information for each quote to ensure fair comparison. The average Arizona renters policy costs around $21 per month according to ValuePenguin, but your actual premium depends entirely on your situation.
Evaluate Deductibles and Coverage Types
When comparing quotes, examine the deductible options carefully; higher deductibles like $1,000 reduce monthly premiums by 15 to 25 percent, but only if you can afford to pay that amount out-of-pocket during a claim. Try replacement cost coverage over actual cash value whenever possible because it reimburses you at current prices rather than depreciated values, which makes a significant difference for electronics and furniture that lose value quickly.
Maximize Discounts and Special Offers
Ask each carrier about bundling discounts for combining renters with auto insurance, which typically saves 8 to 20 percent on renters premiums. Some insurers offer additional discounts for paying annually instead of monthly, installing security features like deadbolts or alarm systems, or living in secured buildings. Insurance Brokers of Arizona® works with over 40 carriers to find options that match your coverage needs and budget, making the comparison process simpler than handling it alone.
Final Thoughts
An Arizona renters policy protects what matters most to you financially. Your belongings represent thousands of dollars in value, your liability exposure is real, and your ability to recover from disaster depends entirely on having proper coverage in place. The cost barrier that stops many renters from acquiring protection simply does not hold up under scrutiny, since Arizona policies start as low as $15 per month-less than most people spend on coffee or dining out.
Bundling renters insurance with auto coverage yields discounts of 8 to 20 percent, and paying annually instead of monthly saves an additional 5 to 10 percent. ZIP code, building type, and coverage limits all affect your premium, so comparing quotes from multiple carriers reveals options you might not expect. We at Insurance Brokers of Arizona® work with over 40 carriers to match your coverage needs with competitive rates, and you can contact us for a fast, free quote tailored to your situation.
Your next step involves getting actual quotes to see what protection costs in your specific situation. Peace of mind comes from knowing your belongings are protected, your liability exposure is covered, and you can recover financially if disaster strikes.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.