Homeowners Policy Arizona: Building A Safeguard For Your Home
Your Arizona home is likely your biggest investment, and protecting it requires the right homeowners policy Arizona coverage. Without adequate protection, a single incident-whether weather damage, theft, or a liability claim-can threaten your financial security.
We at Insurance Brokers of Arizona® help homeowners navigate their coverage options to find policies that actually match their needs. This guide walks you through what Arizona homeowners policies cover, what makes Arizona unique, and how to choose the right protection for your home.
What Arizona Homeowners Policies Actually Cover
Dwelling Coverage Protects Your Home’s Structure
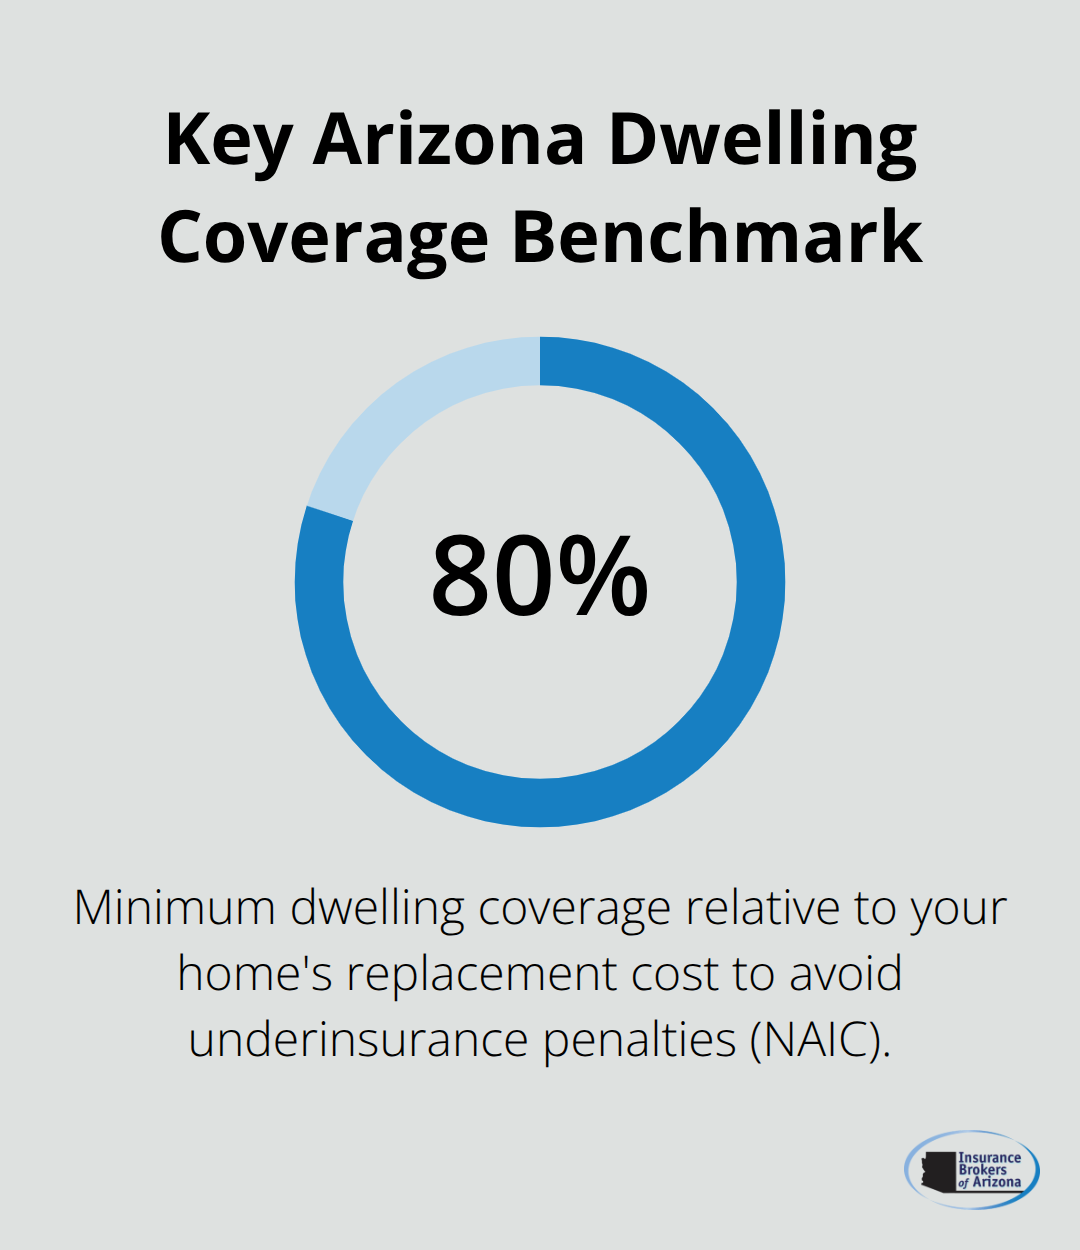
Your homeowners policy in Arizona protects three distinct areas of your property and finances. Dwelling coverage pays to repair or rebuild your home’s structure if fire, windstorms, hail, or theft damage it. Most Arizona policies cover the exterior walls, roof, built-in appliances, and permanent fixtures, but they exclude damage from floods and earthquakes, which require separate policies. The National Association of Insurance Commissioners reports that Arizona homeowners should carry dwelling coverage equal to at least 80% of their home’s replacement cost to avoid underinsurance penalties.
Personal Property Coverage Protects Your Belongings
Personal property coverage protects your belongings inside the home, including furniture, electronics, clothing, and kitchen items. Standard policies typically cover 50-70% of your dwelling coverage amount, though you can increase this if you own high-value items. Jewelry, fine art, and collectibles often hit the policy’s per-item limits, so Arizona homeowners with valuables exceeding $2,500 should consider adding scheduled personal property endorsements.
Liability Coverage Shields You from Financial Risk
Liability coverage protects you financially if someone is injured on your property and sues you for medical bills or damages. Arizona’s minimum liability limits typically start at $100,000, but with the rising cost of medical care and legal judgments, many homeowners should carry $300,000 to $500,000 in protection. This coverage also pays for damage you accidentally cause to someone else’s property, such as accidentally backing into a neighbor’s fence.
Critical Exclusions Arizona Homeowners Must Know
The gap most Arizona homeowners miss is understanding what their policy explicitly excludes. Standard homeowners policies do not cover flood damage, and Arizona’s monsoon season puts thousands of homes at risk each year. The Federal Emergency Management Agency data shows that just one inch of water in your home costs an average of $27,000 in damages. Earthquake coverage is another exclusion, despite Arizona’s seismic activity in areas like the Phoenix metropolitan region. You’ll need to purchase these as separate riders or standalone policies.
Additionally, damage from poor maintenance, wear and tear, or neglect isn’t covered, so keeping your roof, plumbing, and HVAC systems in good condition directly protects your coverage. Arizona homeowners should also know that liability coverage has limits on water damage claims and doesn’t cover intentional acts or business activities conducted from your home. If you run a business (even a small one) from your residence, standard homeowners liability won’t protect you. Damage from poor maintenance, wear and tear, or neglect isn’t covered, so keeping your roof, plumbing, and HVAC systems in good condition directly protects your coverage.
These exclusions matter most before Arizona’s summer monsoon season from June through September, when severe weather claims spike. Understanding what falls outside your coverage is the first step toward identifying the gaps that could leave you exposed. The next section walks you through Arizona-specific risks that shape which policies work best for homeowners in this state.
What Makes Arizona Homeowners Insurance Different
Arizona’s Monsoon Season Demands Specialized Coverage
Arizona’s insurance landscape requires policies built specifically for this environment, not generic coverage designed for other regions. Monsoon season from June through September creates genuine weather hazards that standard policies handle poorly. The National Weather Service reports that Arizona experiences an average of 1,400 lightning strikes annually, with Maricopa County accounting for a significant portion of these strikes. When lightning damages your home’s electrical system or roof, your standard dwelling coverage activates, but the real problem emerges when water follows that lightning strike.
Arizona’s hard, compacted soil fails to absorb water quickly, so even brief monsoons can cause foundation damage costing $10,000 to $25,000 in repairs. Most Arizona homeowners underestimate this risk because monsoons feel brief and intense rather than dangerous. Yet flood damage data shows that just one inch of standing water costs an average of $27,000 in damages. Your policy needs higher water damage limits than homeowners in other states require, or you need separate flood insurance that actually covers the specific damage Arizona monsoons create.

Crime Rates Vary Dramatically Across Arizona Neighborhoods
Beyond weather, Arizona’s property crime rates vary dramatically by neighborhood. According to Arizona Department of Public Safety crime statistics, some Phoenix metro areas experience burglary rates double the national average, while other neighborhoods report significantly lower incidents. This variation means your liability and personal property coverage limits should depend on your specific location, not a statewide standard.
Homeowners in high-crime areas should verify that their personal property coverage includes theft and break-ins, and consider whether standard coverage limits of 50-70% of dwelling coverage actually protect your belongings. If you own a home in central Phoenix or Tempe, your coverage needs differ substantially from someone in Scottsdale or Gilbert. Your address determines your risk profile more than any other factor.
Arizona’s Competitive Market Creates Real Rate Variation
Arizona’s competitive insurance market works in your favor if you shop actively. Major carriers like State Farm, Allstate, and GEICO operate in Arizona alongside regional specialists, creating genuine rate variation. The Arizona Department of Insurance publishes rate comparison data showing that identical coverage can range from $1,200 to $2,100 annually depending on your carrier and location.
Getting quotes from at least three carriers before committing to any policy makes financial sense, because Arizona’s market moves quickly and rates change seasonally. Spring and early summer quotes often run higher than fall quotes because insurers anticipate monsoon claims, so timing matters when you shop. Your specific address, roof age, foundation type, and distance from fire zones all create different quotes from different carriers, making neighborhood-level shopping essential rather than optional.
These location-specific factors set the stage for the next critical decision: how to actually select a policy that matches your home’s unique risks and your financial situation.
Picking the Right Coverage Amount for Your Arizona Home
Determine Your Home’s Replacement Cost, Not Market Value
Start by determining your home’s replacement cost, not its market value-these are dramatically different numbers that most Arizona homeowners confuse. Your home’s market value includes the land, but insurance only covers the structure itself. The Arizona Department of Insurance recommends getting a professional replacement cost estimate from a contractor or appraiser, which typically costs $200–$400 but prevents you from underinsuring by thousands of dollars.
If your home would cost $350,000 to rebuild after total loss, that’s your target dwelling coverage, not the $425,000 you paid for the property five years ago. Dwelling coverage at 80% of replacement cost ($280,000 in this example) triggers underinsurance penalties if you file a claim, so try for 100% coverage or verify your carrier’s specific replacement cost endorsement.
Cover Your Personal Property Accurately
Personal property coverage should reflect what you actually own. Inventory your belongings by room, photograph high-value items, and add scheduled endorsements for jewelry, electronics, or collectibles exceeding standard per-item limits of $1,500–$2,500.
Arizona homeowners with pools, guest houses, or detached structures need additional dwelling coverage riders because standard policies limit coverage on secondary structures to 10–15% of your primary dwelling coverage. This gap catches many homeowners off guard when they file claims on structures they assumed were protected.
Request Quotes with Identical Deductibles
Getting quotes from multiple carriers reveals the actual rate variation in Arizona’s market, and three quotes should be your minimum before selecting any policy. State Farm, Allstate, GEICO, and regional carriers all price identically-structured coverage differently based on their claims experience in your specific neighborhood and zip code.
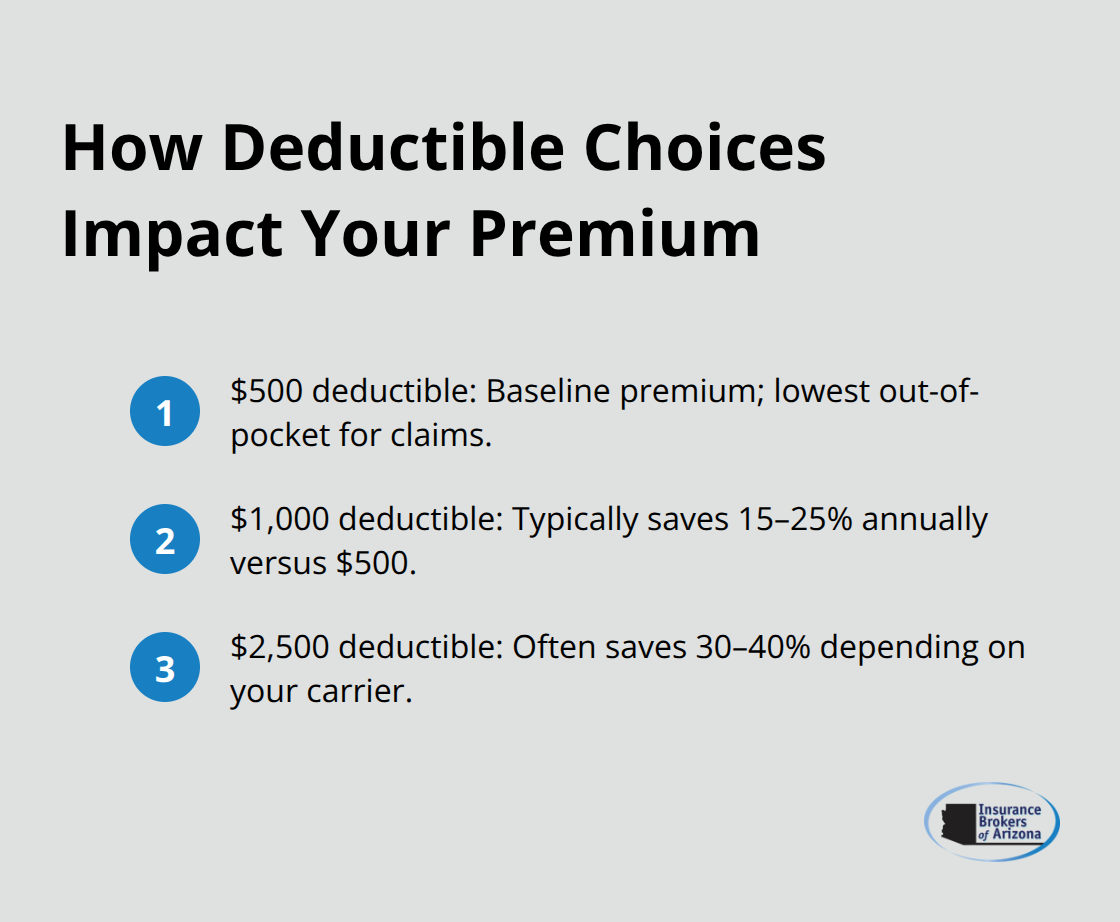
Request quotes with identical deductibles ($500, $1,000, and $2,500) so you can see how deductible changes affect your annual premium. Jumping from $500 to $1,000 typically saves 15–25% annually, while $2,500 deductibles save 30–40% depending on your carrier.
Set Liability Limits Based on Arizona’s Legal Environment
Compare your liability limits honestly against Arizona’s legal environment. Medical costs for slip-and-fall injuries regularly exceed $100,000, and homeowner liability judgments in Maricopa County average $150,000–$300,000 according to court records.
Standard $100,000 limits leave you personally responsible for anything above that threshold, making $300,000 the practical minimum for most Arizona homeowners, with $500,000 preferable if you have a pool, trampoline, or frequently host gatherings. This coverage protects your financial future when accidents happen on your property.
Final Thoughts
Your homeowners policy Arizona protects your financial stability when unexpected events strike your home. The coverage gaps we’ve outlined-from flood exclusions during monsoon season to liability limits that fall short of Arizona’s legal environment-represent real risks that affect real homeowners. Getting this right means understanding your home’s replacement cost, knowing what your policy excludes, and carrying liability limits that match Arizona’s injury and judgment costs.
The practical next step involves gathering quotes from multiple carriers with identical coverage structures so you can see actual rate variation in your market. Arizona’s competitive insurance landscape means your address, roof age, and specific neighborhood determine your rates more than any other factor. Requesting quotes with $500, $1,000, and $2,500 deductibles shows you exactly how much you save by accepting higher out-of-pocket costs, and most Arizona homeowners find that jumping to a $1,000 deductible saves 15–25% annually without creating genuine financial hardship when claims happen.
Working with someone who understands Arizona’s specific risks makes a measurable difference in your coverage quality. We at Insurance Brokers of Arizona® work with reputable carriers to match your home’s unique risks with policies actually designed for this state’s environment, and we handle the comparison work so you don’t contact a dozen carriers individually. Contact Insurance Brokers of Arizona® to secure competitive rates while protecting your investment with coverage that reflects your home’s real value and Arizona’s real risks.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.


