Arizona Insurance Brokers Advice: Your Local Guide to Coverage
Arizona’s desert climate, unique weather patterns, and state-specific regulations create insurance needs that generic national advice simply doesn’t address. At Insurance Brokers of Arizona®, we’ve seen firsthand how residents and business owners miss critical coverage gaps because they don’t have localized guidance.
This guide walks you through Arizona insurance brokers advice tailored to your actual risks-from monsoon damage to liability gaps that could cost you thousands.
Why Arizona’s Insurance Needs Are Completely Different
Monsoons and Desert Hazards Demand Specialized Coverage
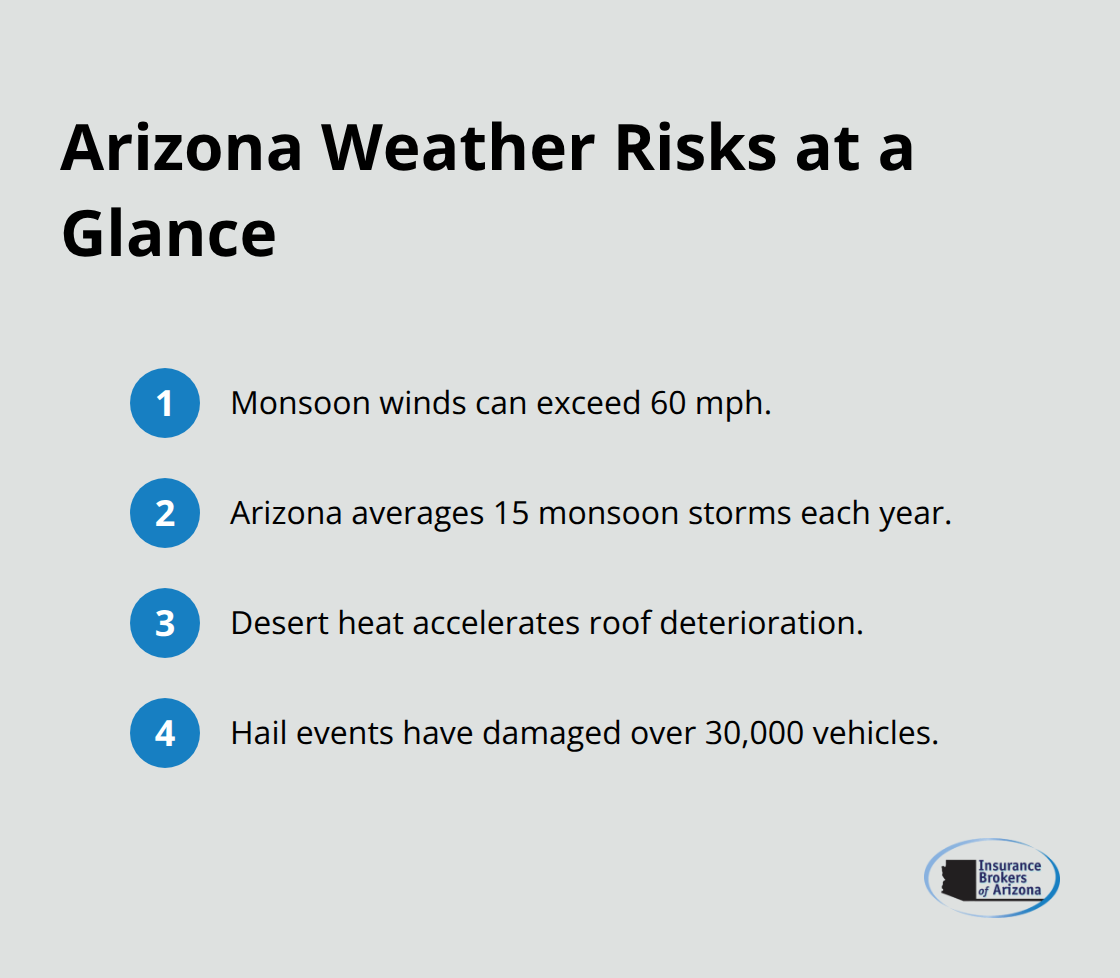
Arizona’s monsoon season brings winds exceeding 60 mph and flash flooding that destroys thousands of homes annually. The National Weather Service reports that Arizona experiences an average of 15 monsoon storms per year, yet most standard homeowners policies don’t automatically cover monsoon damage without specific endorsements. Desert heat causes roof materials to deteriorate faster than in other climates, which means your replacement cost basis needs adjustment every few years. Hail storms in Arizona have damaged over 30,000 vehicles in single events, according to insurance industry data.
Generic insurance advice from national websites or agents in other states misses these Arizona-specific exposures entirely. Most people think their standard policy covers what Arizona weather actually throws at them-and they’re wrong until a claim reveals the gaps.
State Regulations Create Hidden Coverage Requirements
Arizona’s Department of Insurance enforces different liability minimums and coverage rules than most states. Arizona requires minimum auto liability of 15/30/10, which is lower than California but higher than several neighboring states. However, the state also mandates uninsured motorist coverage unless you explicitly waive it in writing, and many drivers don’t understand this requirement.
Commercial general liability policies must comply with Arizona’s specific endorsement requirements for contractors and service businesses. Property tax assessments in Arizona’s high-growth areas like Scottsdale and Phoenix mean your home’s insured value drifts out of sync with replacement costs faster than you’d expect. Business owners often operate with outdated certificates of insurance because they didn’t know Arizona updated its filing requirements in 2023.
Local brokers track these regulatory changes continuously, while national carriers frequently lag in communicating updates to their policyholders.
Local Relationships Accelerate Claims Resolution
When a monsoon destroys your patio or a commercial claim hits your business, you need someone who knows the local adjusters, understands Arizona courts if litigation becomes necessary, and navigates the state’s specific claims process. An agent in another state can’t make those connections or move your claim forward with the same speed.
Insurance Brokers of Arizona® partners with over 40 carriers, which allows matching your specific Arizona risk to insurers who actually specialize in desert properties and monsoon coverage. That relationship translates to faster claims resolution and better outcomes when you need your insurance to actually work.
What Coverage Do Arizona Residents and Businesses Actually Need
Auto Insurance: Going Beyond Arizona’s Minimum Requirements
Arizona requires 15/30/10 liability minimums, but that baseline leaves your assets vulnerable. A single accident causing serious injury can easily exceed these limits, and Arizona’s population growth means congested roads in Phoenix, Scottsdale, and Tempe increase collision risk substantially. We at Insurance Brokers of Arizona® recommend 100/300/100 coverage as a baseline for most drivers, which costs roughly 15 to 20 percent more monthly but protects your wages and savings if someone wins a judgment against you.
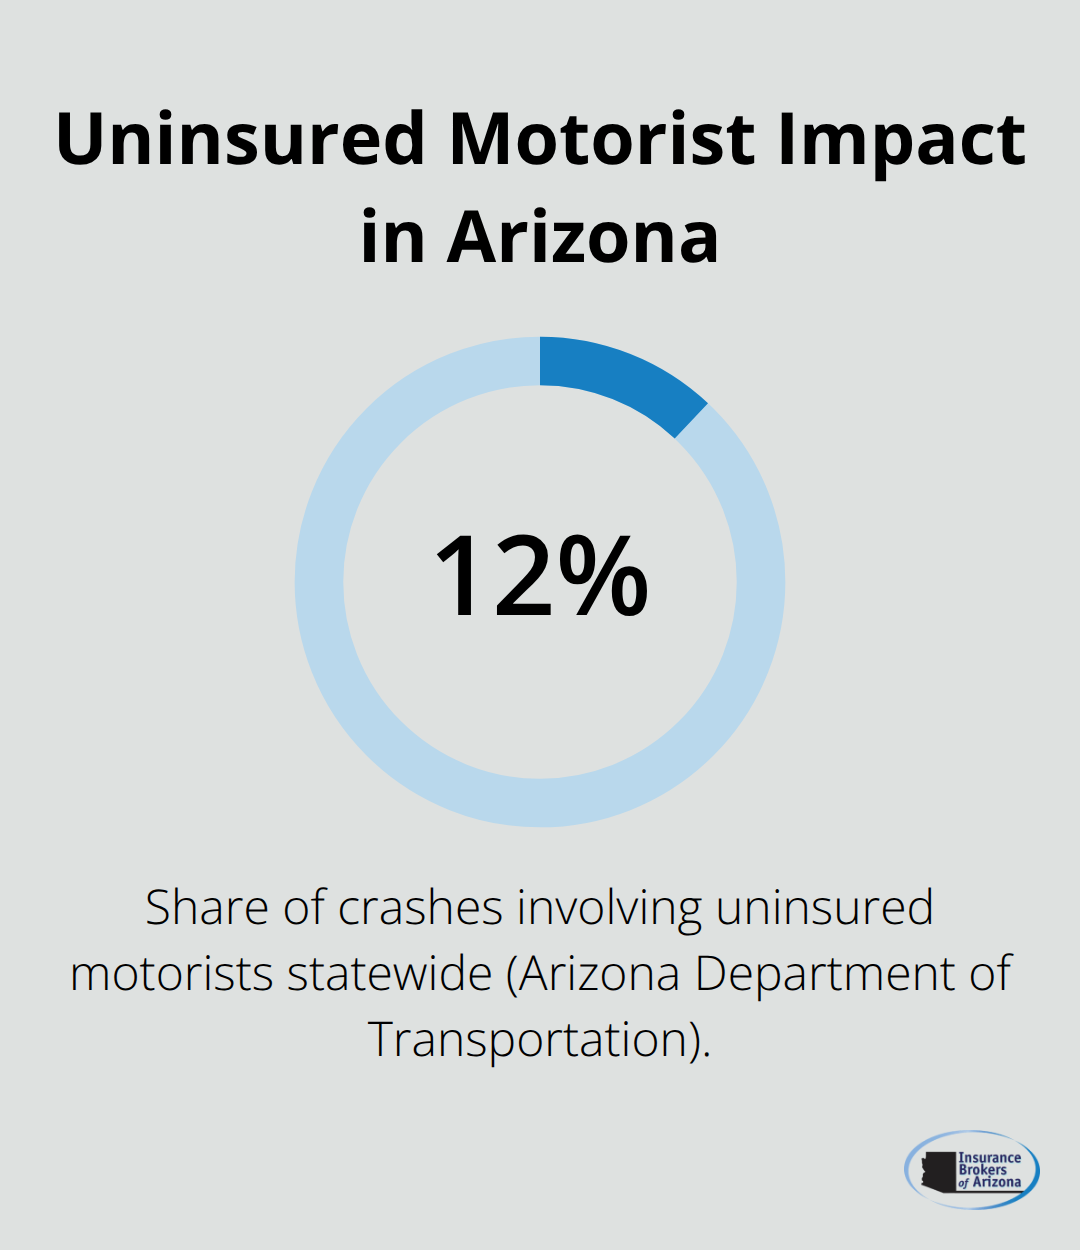
Uninsured motorist coverage is mandatory unless you sign a waiver, yet many Arizona drivers don’t realize they can add uninsured and underinsured motorist protection that mirrors their liability limits. This matters because the Arizona Department of Transportation reports that uninsured motorist accidents account for approximately 12 percent of crashes statewide. Adding this protection costs far less than the financial devastation an uninsured driver can cause.
Home Insurance for Desert Properties Requires Specific Adjustments
Your replacement cost basis needs updating every two to three years because Arizona’s rapid property value appreciation means your coverage limit falls behind actual rebuilding costs. Standard homeowners policies exclude monsoon damage, so you need specific wind and hail endorsements that cost between 50 and 150 dollars annually depending on your roof age and location.
Roof condition matters tremendously in Arizona because intense sun exposure degrades asphalt shingles in 15 to 20 years instead of the 25-year lifespan typical elsewhere. If your roof exceeds 15 years, most carriers either refuse coverage or demand expensive upgrades. This Arizona-specific reality catches many homeowners off guard when they attempt to renew their policies.
Business Insurance Tailored to Arizona Operations
Business owners operating in Arizona need commercial general liability that accounts for industry-specific exposures, particularly contractors, landscapers, and service businesses working in extreme heat environments. Workers compensation requirements vary significantly based on employee count and classification, and Arizona’s construction industry faces higher claim frequencies than national averages.
The state mandates specific coverage for any business with employees, making annual policy reviews non-negotiable as your operation changes. Coverage gaps in commercial policies often stem from outdated endorsements or misaligned industry classifications. These gaps expose your business to liability that your policy won’t cover when claims arise.
Where Arizona Property Coverage Actually Falls Short
Replacement Cost Basis Lags Behind Rapid Property Appreciation
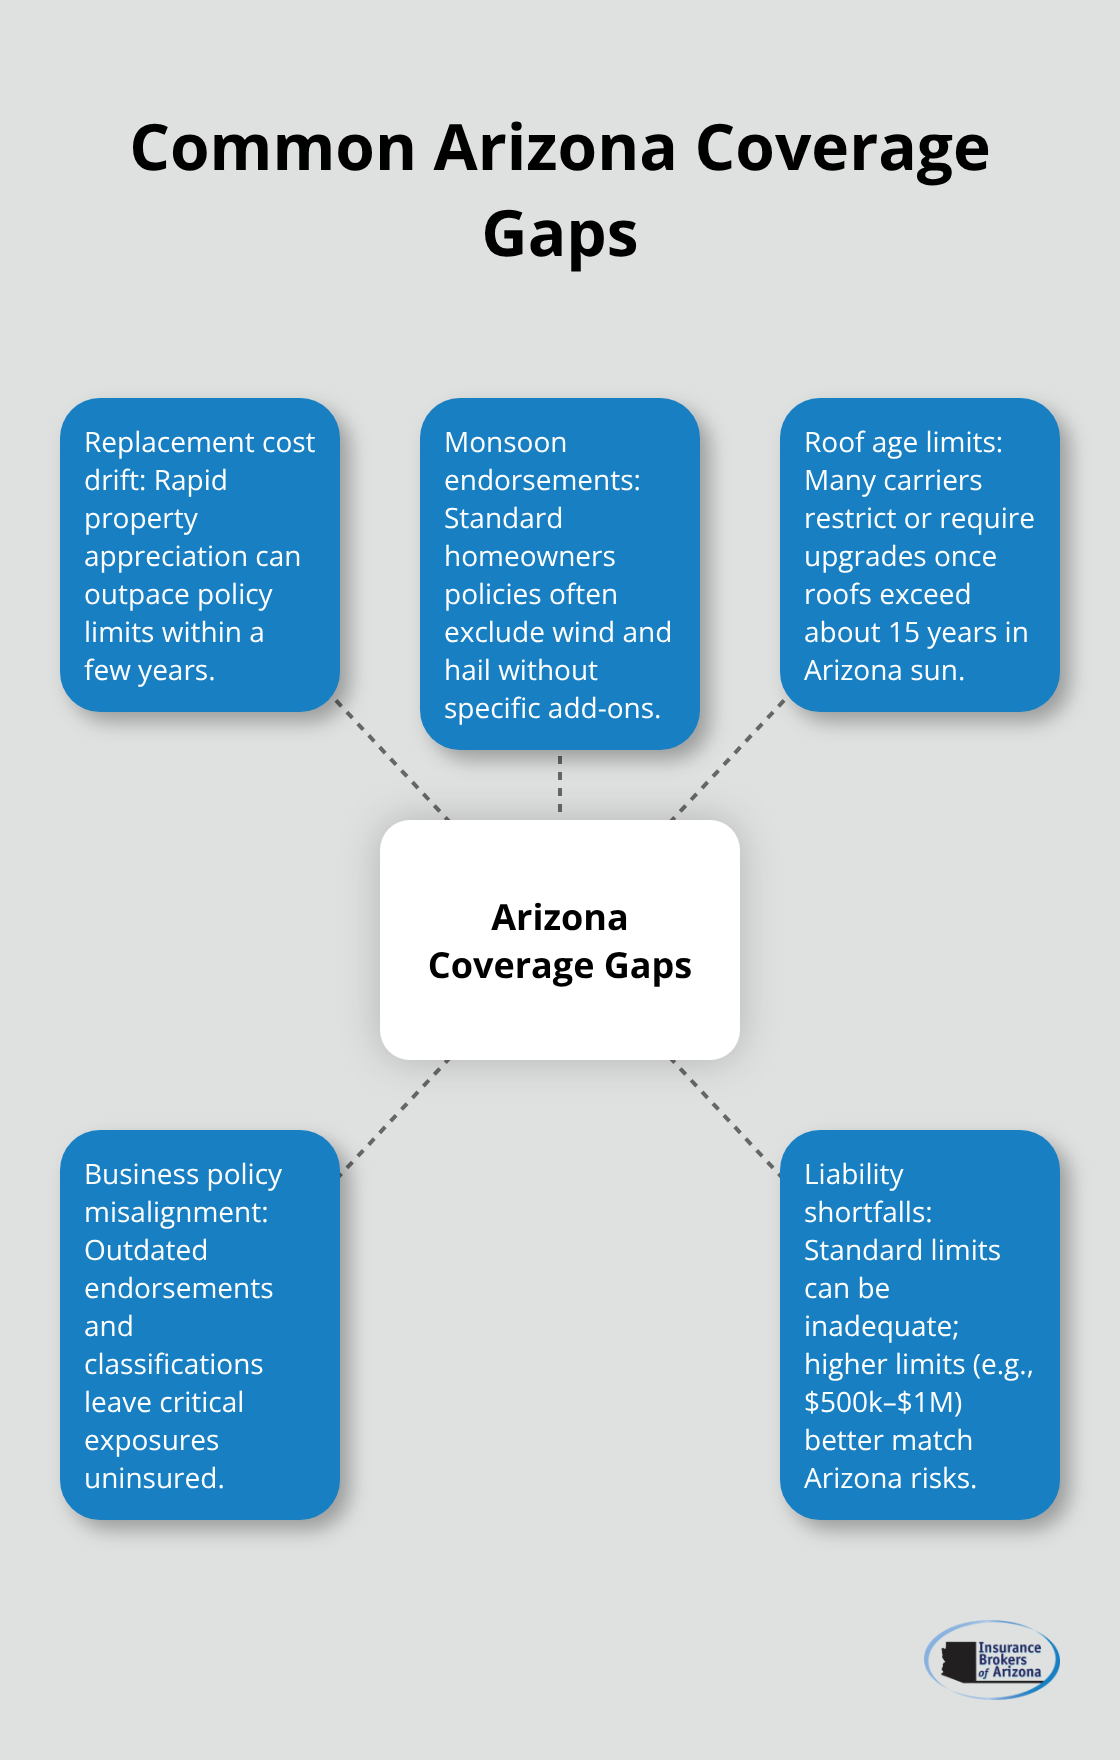
Arizona’s rapid property appreciation creates a dangerous gap between what homeowners think they’re insured for and what their policies actually cover. Home values in Phoenix increased approximately 35 percent between 2020 and 2023 according to Zillow data, yet most homeowners never adjust their replacement cost basis to match this growth. Your policy’s insured value becomes outdated almost immediately after purchase, leaving you severely underinsured if a total loss occurs. A homeowner with a 400,000 dollar policy purchased in 2021 now owns a property worth 540,000 dollars, but their coverage limit hasn’t budged.
When monsoon damage or a fire destroys the home, that 140,000 dollar gap comes directly from your pocket.
Monsoon and Weather Endorsement Gaps Leave Homes Vulnerable
Most standard homeowners policies exclude monsoon damage, yet Arizona experiences 15 average monsoon events annually, and each one brings wind damage that costs thousands to repair. Adding wind and hail endorsements costs 50 to 150 dollars yearly depending on roof age and location, but homeowners skip this because they assume their standard policy covers weather damage. Roof age determines whether carriers will even offer coverage in Arizona, since intense sun exposure degrades materials in 15 to 20 years rather than the 25-year lifespan typical nationally. A homeowner with a 16-year-old roof discovers this limitation only when renewal time arrives and insurers refuse to renew or demand expensive upgrades.
Business Property Values Drift Out of Sync with Operations
Business owners in high-value commercial areas commit similar errors by failing to update their property values annually as their operations expand or inventory increases. A landscaping business that added equipment and trucks without increasing their commercial property coverage limits faces partial reimbursement if theft or weather destroys their assets. Workers compensation requirements change annually as classifications and payroll shift, yet many business owners renew policies without reviewing whether their coverage matches their current operations.
Liability Protection Gaps Create Catastrophic Exposure
Liability protection gaps hit harder than property underinsurance because a single lawsuit can exceed your entire home value. Arizona’s population density in Phoenix and Scottsdale means liability claims spike during peak seasons, yet many homeowners carry minimum liability limits of 100,000 to 300,000 dollars when 500,000 to 1,000,000 dollars provides necessary protection. A guest injured at your pool, a contractor hurt on your property, or someone harmed by your dog can easily generate medical bills and legal judgments exceeding standard policy limits.
Business owners operating in Arizona face even steeper liability exposure because commercial claims from customers, employees, or third parties can bankrupt an operation carrying inadequate protection. Outdated endorsements, misaligned industry classifications, and coverage gaps won’t appear until a claim reveals what wasn’t protected.
Final Thoughts
Arizona insurance brokers advice matters most when you face a claim or discover coverage gaps that cost thousands. National carriers and online quote tools cannot replicate what local expertise delivers, and that difference compounds every time your policy renews or a loss occurs. We at Insurance Brokers of Arizona® work with over 40 carriers, which allows us to match your specific Arizona risks to insurers who understand monsoon exposure, desert property appreciation, and state-specific regulations that protect your actual assets.
Claims support separates local brokers from distant customer service lines when a monsoon destroys your roof or a commercial claim hits your business. You need someone who knows Arizona’s adjusters, understands local court processes, and accelerates resolution through established relationships. A broker in another state cannot make those connections or move your claim forward with the same speed that matters when you need your insurance to work.
Coverage gaps and opportunities emerge during annual reviews when we examine whether your liability limits match your actual exposure, whether your property values reflect current market conditions, and whether your endorsements cover Arizona’s specific weather threats (most people never review these details until a claim reveals what wasn’t protected). Insurance Brokers of Arizona® provides personalized guidance that protects your finances and eliminates the stress of wondering whether your coverage is adequate.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.


